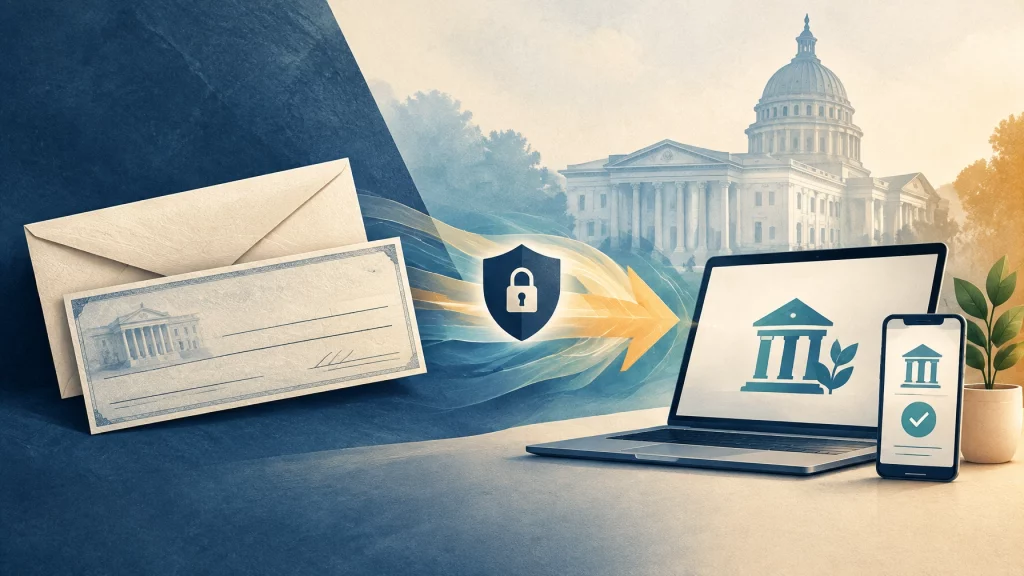
The quick version: H.R. 9214, called the TSP Modernization Act, would make it possible to transfer eligible money from the Thrift Savings Plan (TSP) to a qualified retirement plan electronically. That could make consolidating retirement accounts easier for some federal employees and retirees.
But the bill is not law. As of November 6, 2026, it remains in the House Committee on Oversight and Government Reform, where it was referred after its introduction on June 9. It has not passed Congress.
If you’re weighing a TSP rollover, the proposed change may be worth watching, but you’ll need to work with today’s process for now.
Why is a TSP rollover still tied to a paper check?
When federal employees leave service or retire, some consider moving eligible TSP savings to an IRA or another eligible retirement plan. One reason may be to bring accounts together. Another may be to coordinate how they manage their retirement savings.
Today, a direct rollover from the TSP to an IRA generally involves a U.S. Treasury check payable to the receiving IRA or plan. The receiving financial institution must confirm that it will accept the funds and provide the required information for the TSP distribution request. The TSP’s rollover fact sheet explains the current process.
That check is not necessarily a check made out to the participant. But it still means a paper instrument has to be issued and handled as part of the transfer. Completing the steps, resolving missing or mismatched information, and getting the check to the right destination can add friction and time.
The TSP already allows electronic deposits for some payments sent to a participant’s personal checking or savings account. A direct rollover to another retirement plan is different: the money is moving from one retirement account to another, and the current process generally relies on a check.

What would H.R. 9214 change?
The bill would let an otherwise permitted transfer from a TSP account to a qualified retirement plan at a brokerage firm be made electronically. The participant would first need to provide the information required to carry out the transfer.
In practical terms, it aims to give the TSP a way to move eligible rollover money digitally instead of relying on a paper check. That could make the process more convenient and reduce some of the handling steps.
There are two important limits to keep in mind:
- It would create an electronic option; it does not say paper checks must disappear. The bill says such a transfer “shall be permitted” electronically. That means the electronic method would need to be available for qualifying transfers, not that every transfer must happen electronically.
- It would not make new transfers eligible. The bill applies when a transfer is otherwise permitted. It does not change the underlying rules about who can roll over money or which funds qualify.
The bill also calls for a report to Congress on implementation one year after enactment. Its electronic-transfer provision would take effect one year after enactment as well, not one year after the bill was introduced. Read the text of H.R. 9214 on Congress.gov.
Who might be affected?
The change could matter to eligible TSP participants considering a rollover, including current or former employees of the U.S. Postal Service (USPS), Department of Veterans Affairs (VA, sometimes called the Veterans Administration), Department of Defense (DOD), Department of Labor (DOL), and Social Security Administration (SSA).
It may be especially relevant to federal retirees who are comparing whether to keep their savings in the TSP or consolidate eligible assets elsewhere. For FERS employees, the TSP is one part of a broader federal retirement picture. H.R. 9214 would address a transfer process. It would not change FERS benefits, the TSP’s investment options, or withdrawal eligibility.
A simple example: imagine a retired federal employee who has decided, after reviewing the tradeoffs, to move an eligible TSP balance to an IRA. Under today’s process, the transaction generally involves a Treasury check. If H.R. 9214 became law and the electronic system were implemented, an eligible transfer could instead be made electronically. The participant would still need to provide the required information and meet the existing rollover rules.

What the bill would not do
The name “TSP Modernization Act” may sound broad, but this 2026 proposal is narrow. It is about how certain transfers are carried out, not a general rewrite of the Thrift Savings Plan.
If passed, H.R. 9214 would not:
- Automatically move anyone’s TSP balance.
- Require participants to roll money out of the TSP.
- Expand eligibility for rollovers or withdrawals.
- Change TSP contributions, investment choices, or account balances.
- Guarantee that every transfer would be faster or free of processing delays.
The bill’s name is also similar to the 2017 TSP Modernization Act, which became law and changed certain withdrawal rules. H.R. 9214 is a separate proposal with a different, more focused purpose.
What should federal employees and retirees do now?
Since H.R. 9214 has not become law, don’t plan on an electronic TSP-to-IRA rollover being available because of this bill. If you’re considering a transfer today, use current TSP procedures and verify details with both the TSP and the receiving IRA provider.
A few practical steps can help:
- Confirm that a rollover fits your overall plan. Keeping money in the TSP and moving it to an IRA can each have advantages and tradeoffs. Compare investment choices, fees, services, withdrawal rules, and your need for flexibility.
- Check that the receiving account can accept the specific funds. Traditional and Roth balances can have different rollover rules. Ask the receiving institution what it can accept and what information it requires.
- Follow current TSP instructions. The TSP’s distribution information explains how payments are handled. Don’t assume the receiving provider’s form can replace the TSP’s required process.
- Keep records and allow time for processing. Save copies of submitted information and confirm the destination account’s instructions before starting. A check-based process may require additional coordination.
If you’d like help understanding how a potential rollover fits alongside your federal benefits and retirement goals, you can book a benefits review with Federal Benefits Service. We can help you sort through the questions to ask and the tradeoffs to consider.

The bottom line
H.R. 9214 could modernize one part of the TSP rollover process by making electronic transfers available for certain eligible transfers to qualified retirement plans. That may eventually offer a simpler alternative to a process that generally uses a Treasury check.
For now, though, it is a proposal, not a new TSP feature. As of November 6, 2026, the bill remains in committee. Follow its status on Congress.gov, and rely on current TSP rules if you’re planning a rollover.
A transfer method is only one part of the decision. If you’re reviewing your federal retirement options, schedule a benefits review to discuss your questions and next steps. Any rollover decision should take your individual circumstances, plan rules, and tax considerations into account.